TaxesGlobal Mobility
UK Budget 2026: What It Means for Americans in the UK
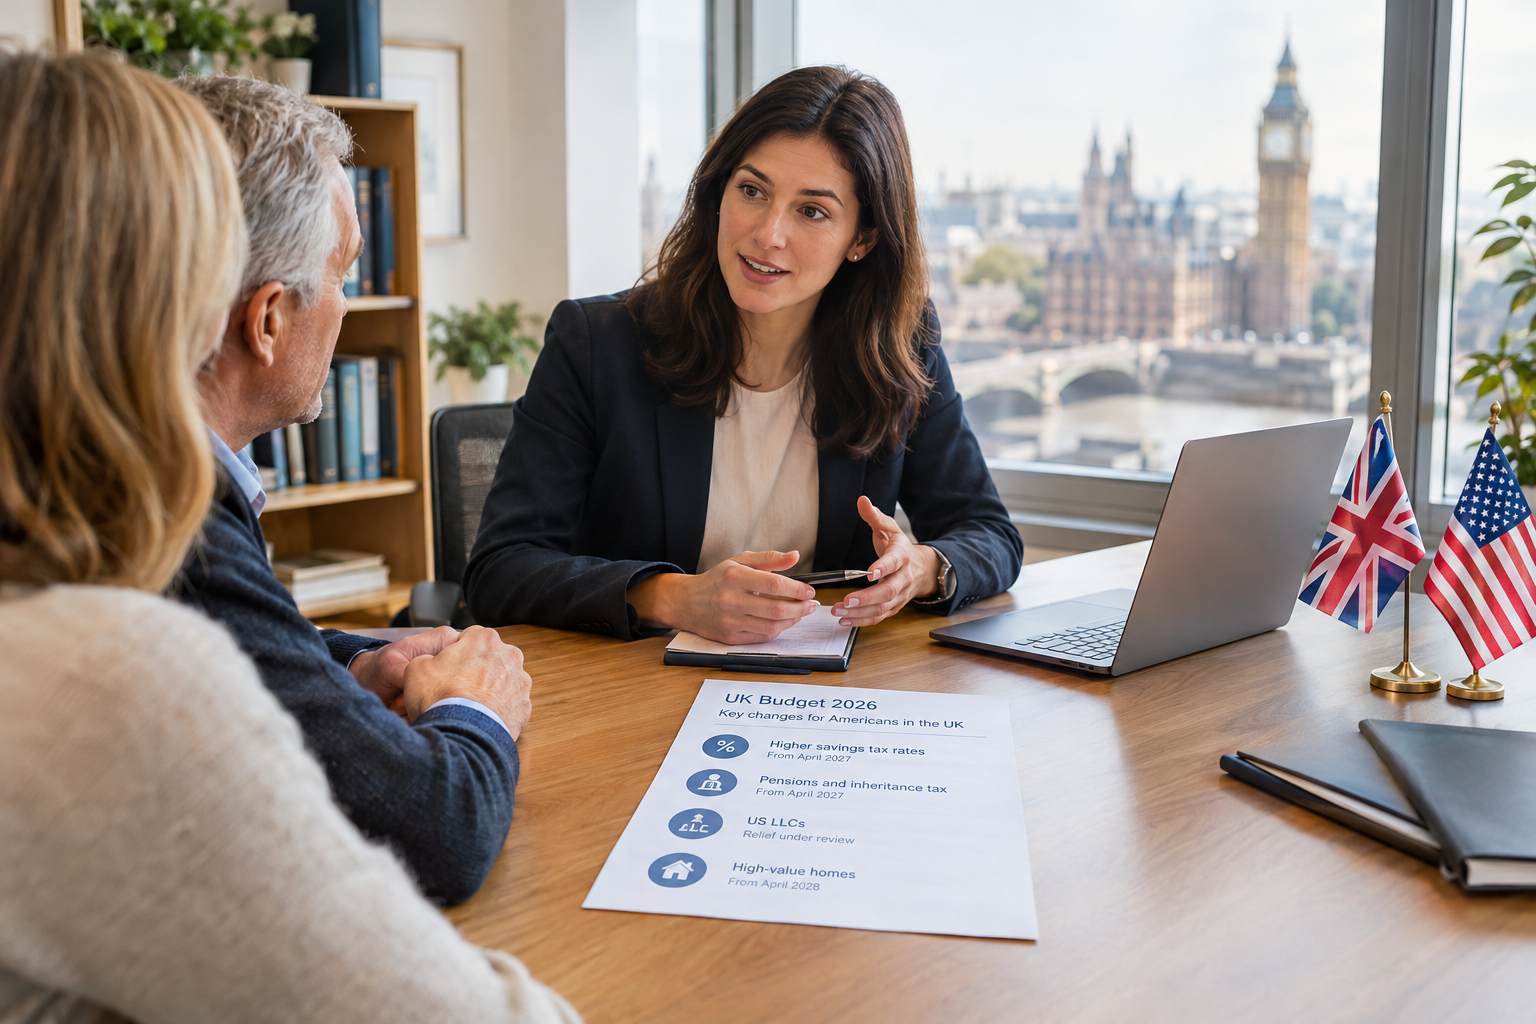
The 28 October Budget raises tax on savings income, keeps pensions on course for inheritance tax and lists relief for US LLC owners. What advice firms should check with each American client in the UK.
Advising clients in this situation? Get a sample client report
UK Budget 2026: What American Expats and Their Financial Advisers Need to Know
The UK Budget announced on 28 October 2026 brings changes that matter to Americans living in the UK, particularly those managing savings, pensions and investments across two tax systems.
For financial advisers, the challenge is understanding how these changes affect clients who may need to report the same income or assets in both countries. Here are the main changes to know, and what to review with clients before 5 April 2027.
The key takeaways
- Savings tax rates are rising. From 6 April 2027, UK tax rates on savings income will increase to 24%, 44% and 49% for basic, higher and additional rate taxpayers.
- Pensions are still due to enter inheritance tax calculations. Most unused pension funds and death benefits will come into scope from April 2027.
- Relief for US LLC owners is being explored. HMRC has confirmed its intention to develop a mechanism to address double taxation, but the details and implementation need to be confirmed.
- The £20,000 cash ISA limit remains. The Budget cancelled the previously planned reduction to £12,000 for under-65s.
What stays the same?
Several key allowances and rates remain unchanged:
- The personal allowance remains £12,570, and the main income tax bands remain frozen.
- The standard inheritance tax rate remains 40%, with a £325,000 nil-rate band.
- The main capital gains tax rates remain unchanged.
- The pension annual allowance remains £60,000, and the lump sum allowance remains £268,275.
The UK's foreign income and gains (FIG) regime, introduced in April 2025, also remains in place. Qualifying new UK residents who have spent at least ten consecutive tax years outside the UK may claim relief on eligible foreign income and gains for up to four years.
American citizens generally continue to have US tax filing obligations wherever they live. Depending on their circumstances, these can include US income tax returns, FBARs and Form 8938.
Four Budget changes to discuss with clients
1. Higher tax on savings income
From 6 April 2027, the UK tax rates on savings income will rise by two percentage points:
- Basic rate: 24%
- Higher rate: 44%
- Additional rate: 49%
For American clients, UK bank interest may also need to be reported on their US tax return. The higher UK tax could affect the foreign tax credits available against their US liability, depending on their circumstances.
What to review: UK and US savings accounts, expected interest income, and how the client and their accountant plan to claim foreign tax credits.
2. Cash ISAs remain at £20,000
The Budget cancelled the planned reduction in the annual cash ISA allowance. The limit remains £20,000 for all ages, alongside the overall annual ISA subscription limit of £20,000.
However, ISAs generally do not receive the same tax-free treatment under US tax rules as they do in the UK. American clients should understand the US reporting and tax implications before deciding how much to hold in an ISA.
What to review: Cash and stocks and shares ISA holdings, the underlying investments, and their US tax treatment.
3. Pension funds and inheritance tax
From 6 April 2027, most unused pension funds and pension death benefits will come into scope of UK inheritance tax, subject to specific exclusions.
The Budget also removed the two-year rule under which certain otherwise tax-free pension death benefits could become taxable if paid too late. That change applies to relevant payments made on or after 28 October 2026.
These are separate changes, and advisers should consider both the inheritance tax position and the income tax treatment of death benefits.
What to review: Pension balances, beneficiaries, estate plans and the potential impact on UK inheritance tax. For American clients, cross-border estate and pension advice may also be needed.
4. Potential relief for US LLC owners
US LLCs can create difficult tax outcomes for UK residents because the US and UK may classify and tax the same entity differently. This mismatch can lead to double taxation.
Following its consultation, HMRC has confirmed that the government intends to develop a mechanism to provide double-taxation relief for affected individuals. The detailed rules and implementation should be checked before assuming a client qualifies.
What to review: US LLC interests, how income is currently taxed in each country, and whether the proposed relief may apply. Clients should discuss their position with a cross-border tax specialist.
One more change: high-value UK homes
From April 2028, an additional annual council tax surcharge will apply to owners of residential properties in England worth £2 million or more. The charge will depend on the property's valuation band.
For American clients with high-value UK property, this is worth including in longer-term financial planning.
What advisers should check before 5 April 2027
Use the end of the UK tax year to review each client's position:
- Savings: Which UK and US accounts earn interest, and how much?
- ISAs: What does the client hold, and how are those investments treated for US tax purposes?
- Pensions and estates: Are beneficiaries and estate plans up to date ahead of the April 2027 changes?
- US LLCs: Could the client be affected by the UK-US classification mismatch?
- Tax filings: Are US returns, FBARs and Form 8938 filings up to date, where required?
Not every change will affect every client. The key is to understand the client's full financial picture before deciding what needs attention.
How Aequify helps advice firms
Aequify brings clients' UK, US and international accounts into one view, helping advisers build a clearer picture of their clients' finances.
It also turns financial information into tax-ready data packs for accountants, helping reduce manual work and making it easier to identify issues that need a closer look.
With a tax outlook and scenario planner, advisers can use that information to have more informed conversations with clients about their cross-border finances.
This article is for general information for financial advisers and is not tax, legal or investment advice. Some Budget measures require legislation or further guidance. Confirm the current rules and their application to each client with a qualified cross-border tax adviser.