Personal FinanceGlobal Mobility
Held-Away Assets Abroad: How Advice Firms See the Whole Client
Expat clients keep accounts your firm cannot see, in other institutions and other countries. Why held-away assets matter for planning, consolidation and reporting, and four steps to one view of each client.
 Aequify Team
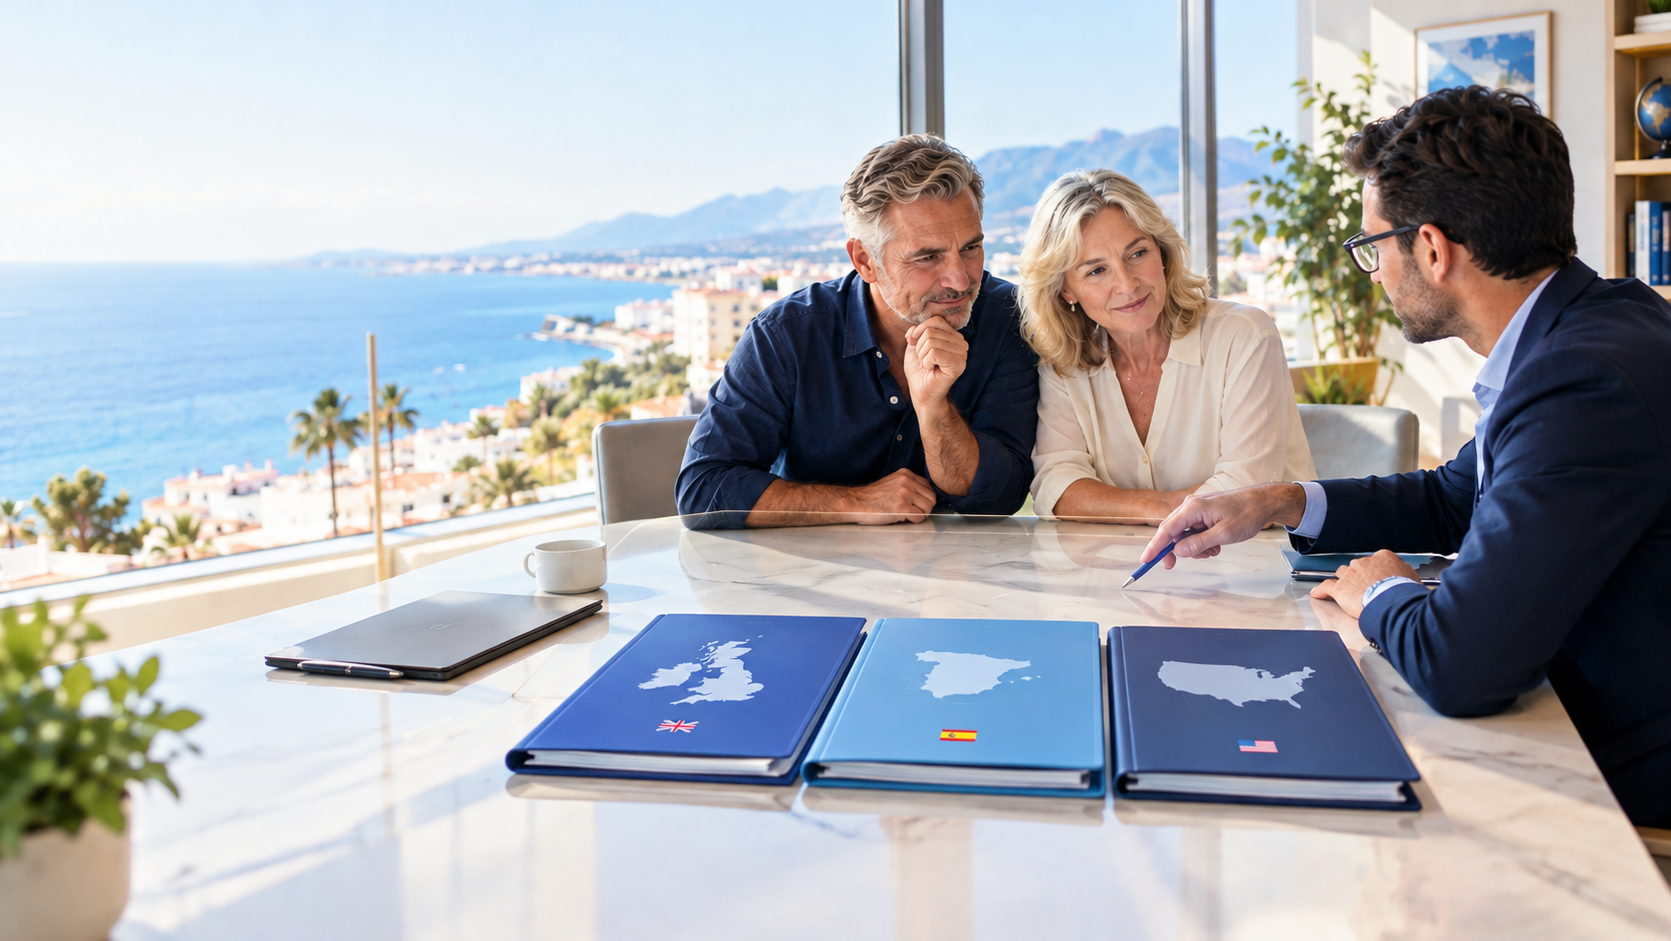
An expat client rarely keeps everything with one firm. A British and American couple on the Costa del Sol might hold a Spanish bank account, a UK pension, a US brokerage account opened before the move, and savings they forgot to mention.
Your firm manages part of that. The rest is held away, in other institutions and other countries, and it shapes every recommendation you make.
Why held-away assets matter to an advice firm
- Planning
Retirement income, inheritance and currency advice are only as good as the balance sheet behind them. A plan built on part of a household answers a narrower question than the client is asking. - The next conversation
Assets held elsewhere are where consolidation and fee discussions start. When a client sees every account side by side, duplicated costs and idle cash are easier to talk about. - Accounts at risk
Some US brokers restrict or close accounts for customers who live abroad. A client may not know until a trade is blocked. See our overview of US custodians closing non-resident accounts and our Fidelity guide. - Reporting in two countries
The same accounts feed the client's filings. American clients report foreign accounts on the FBAR once their combined value passes $10,000 at any time in the year, and may also file Form 8938. Spanish residents report foreign assets on Modelo 720 when a category exceeds €50,000. Missing balances come back to the adviser as questions.
Why firms usually cannot see them
Clients forget accounts, hold them in several currencies, and send statements as PDFs at different times of the year. Each country's institutions report differently, and no single feed covers a Spanish bank, a UK platform and a US broker.
The result is a client file that is accurate for the assets you manage and a guess for everything else.
Four steps to one view of each client
- Ask for every account
Not only investable assets: bank accounts, brokerage, pensions, insurance wrappers and property, in every country the client has lived or worked. - Record the basics for each
Institution, country, currency and owner, so you can group the household by jurisdiction and spot gaps. - Connect what you can, upload the rest
Live connections keep balances current without chasing. Statements fill in institutions that cannot be connected. - Review the whole picture at each meeting
What moved, what is at risk, and what the client's accountant will need next.
Where the adviser's role stops
Seeing the whole client does not turn an advice firm into a tax firm. Preparing and signing filings stays with the client's qualified tax adviser. Your firm's role is to hold a complete, current picture and hand the accountant clean numbers.
Advising American clients in Spain? Our compliance checklist for wealth firms lists what to collect for each filing.
How Aequify helps advice firms
Aequify gives your firm one view of each client's accounts across countries, including assets held elsewhere, and turns them into tax-ready data packs for the client's accountant. A tax outlook and a scenario planner give you a reason to talk to clients about retirement, moves and other life events.
This article provides general information for advisers, not tax, legal or investment advice. Reporting requirements and thresholds can change, so confirm the rules with a qualified tax adviser for each client.